


Money
Coins
There are five types of coins:
Gold Coin: This is approximately 1/8 of a troy ounce of gold. A gold coin is worth the equivalent of 300$ circa 2019. Gold coins are not commonly in circulation, as most gold is diverted for jewelry and for gold gilding in items of magical defense.
Bronze Coin: This is approximately 1/4 of a troy ounce of bronze. A bronze coin is worth the equivalent of 60$ circa 2019.
Silver Coin: This is approximately 1/4 of a troy ounce of silver. A silver coin is worth the equivalent of 12$ circa 2019.
Copper Coin: This is approximately 1/2 of a troy ounce of copper. A copper coin is worth the equivalent of 2.40$ circa 2019.
Penny: This is approximately 1/8 of a troy ounce of copper. A penny is worth the equivalent of .60$ circa 2019.
1 Gold Coin= 5 Bronze Coins= 25 Silver Coins= 125 Copper coins= 500 Pennies
1 Bronze Coin= 5 Silver Coins= 25 Copper Coins= 100 Pennies
1 Silver Coin= 5 Copper Coins= 20 Pennies
1 Copper Coin= 4 Pennies
All coins have a ridge on the edge to ensure they do not have pieces shaved off of them. They also all have the castle of the country they are from imprinted on one side, and the king's profile imprinted on the other. Coins can be used in whatever country, even if they have the king or castle of a different country imprinted on them. This is because the weight of the coins is the same across the countries, even non-Altruist countries. The coins are used normally in trade, no matter the country, and then when the coins go through banks, tax collectors, or government officials, the coins are weighed, to ensure authenticity, and re-stamped to have the official images of the country.
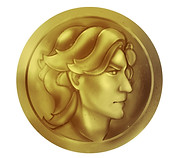

The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. On the back, it has the castle of the City of the Librarians, which is famous for being a floating, teleporting city.
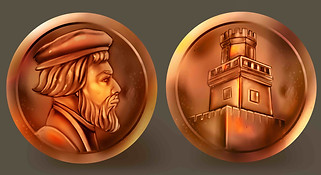
The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. He founded the organization of the Librarians in 105 BGB. On the back of the coin, it has the castle of the City of the Librarians. This city is famous for being a floating, teleporting city.


The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. On the back, it has the castle of the City of the Librarians, which is famous for being a floating, teleporting city.
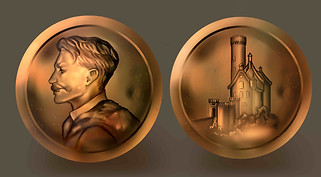
The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. On the back, it has the castle of the City of the Librarians, which is famous for being a floating, teleporting city.
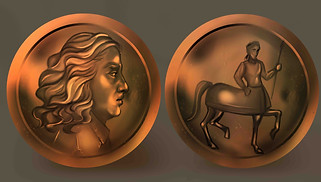
The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. On the back, it has the castle of the City of the Librarians, which is famous for being a floating, teleporting city.
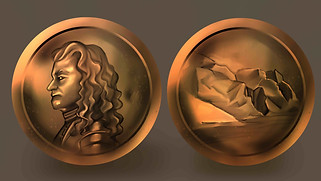
The gold coin shows the likeness of Solomon Anguis, the founder of the Librarians on the front. On the back, it has the castle of the City of the Librarians, which is famous for being a floating, teleporting city.
Vouchers
One gold coin voucher is the equivalent value of one gold coin. A gold coin, and therefore a gold coin voucher, is the equivalent of 300$ circa 2019.
In Altruist Allied countries gold coin vouchers are used as a type of cash currency. Gold coin vouchers are treated as the equivalent of a gold coin. Gold vouchers are the preferred method of currency to gold coins. This is because the government and banks prefer to use gold for other purposes, mainly in jewelry and to protect from magic (Gold acts as an insulator against magic).
Gold coin vouchers can be traded in for a gold coin at any bank. However, it takes a lot of paperwork, and a waiting period of a month to get the vouchers exchanged. Vouchers can be exchanged immediately, without a month waiting period, but a ten percent charge is added to the rushed request. Therefore, a person either has to wait a month to get an actual gold coin in exchange for a voucher or receive only four bronze, two silver, two copper, and two pennies in exchange for each voucher. Because of this inconvenience, people rarely go through the process of exchanging the voucher for the actual gold coin.
Vouchers are generally not considered legal tender in non-Altruist countries. However, near border establishments that do a lot of trade with Altruist Allied countries, vouchers are accepted as non-legal currency. While gold coins, jewels, gems, and other commodities are used for trade between Altruist and non-Altruist countries, non-Altruist governments sometimes use acquired vouchers for trade as well. Non-Altruist countries generally accept vouchers for porta lunae travel, but also apply a three silver transaction cost per voucher for travel, and for official exchanges of vouchers for gold coins.
Magic Gems
Magic gems are used as a form of bartering or monetary exchange in non-Altruist-controlled countries. Altruist governments also sometimes use magic gems to trade with non-Altruist governments and establishments. However, using magic gems as a form of bartering or monetary trade is technically illegal in Altruist Allied countries, as a magic tax is applied to the exchange of all magic gems and magic-related charms and wares. It can technically be done if the tax is applied to the exchange. But without paying the tax, the bartering, buying, selling, or monetary exchange of magic gems or magic charms and wares is illegal in Altruist Allied countries.
Because of the tax on all magic gems, the cost of magic gems is standard in Altruist Allied countries. Pricing is based on the boltage of the gems. The pricing is as follows:
Flammesten, 4-bolt: 3 silver (36$)
Vindsten, 4-bolt: 5 silver (60$)
Vandsten, 4-bolt: 7 silver (84$)
Solsten, 4-bolt: 4 silver (48$)
Grundsten, 4-bolt: 20 silver (240$)
Manesten, 4-bolt: 30 silver (360$)
Natursten, 4-bolt: 20 silver (240$)
Issten, 4-bolt: 20 silver (240$)
Lynsten, 4-bolt: 30 silver (360$)
A 10% tax is applied to flammesten. A 20% tax is applied to the other gems.
Pricing is not standardized in non-Altruist countries and is dependent on the different counties' access to the different kinds of gems.
Jewels
Jewels are used not just for jewelry, but also as an alternative means of bartering and monetary trade. Jewels are used in particular for multi-coin level trades, such as when purchasing houses, horses, carriages, etc. According to law, when a jewel is used in trade, both parties are allowed to bring in a licensed appraiser to give an estimate of the value. However, there is no official value for jewels, and the parties must decide for themselves the value of the jewels used for their trade.
There are no taxes associated with using jewels for bartering or monetary trade unless the jewels are set in some form of jewelry. Then there is a 10 % tax associated with bartering, buying, selling, or monetary trade in regards to jewelry. Because of this, loose gems are most commonly used for trade, as no tax is associated with the bartering, buying, selling, or monetary trade of loose gems. If jewelry is used for bartering or monetary trade, at least one licensed appraiser is required to appraise the value of the jewelry. As many appraisers as the parties desire may be consulted. The decided value of the jewelry between the parties must be within two bronze of any of the appraisers' estimates. A tax is applied to the decided value, and at least one party must sign documents to that decided value. The tax paperwork is to be filled out by the appraiser, who files the taxes. The parties can decide between themselves as to who pays the tax, or if it is split by them. The parties also can decide who pays the appraiser.
All jewelry stores or merchants must work with at least one licensed appraiser. However, the appraiser does not need to be on staff for all operating hours. A licensed appraiser may work for multiple store locations, as long as he or she can visit the store at least once a month and fulfill the monthly paperwork requirements for jewelry taxes and appraisals.
If a store or merchant only sells loose gems, they do not need to have a licensed appraiser. However, a buyer or seller may bring in a licensed appraiser to help establish the value of the loose gem. No tax is applied to the buying or selling of loose gems. Because of this loose gem trading is the primary avenue of trade between vendors, with jewelry made locally. Traveling jewelry merchants can also go to different cities and pay for a temporary business permit to sell jewelry in different cities. Famous jewelers may travel to various cities during the duration of the festival to sell their jewelry while maintaining their own stores in larger cities. Because of this, jewelry buyers in smaller cities may seek out traveling jewelry merchants during festivals to gain access to unique and well-done pieces.
It is to be noted, that it is not uncommon for gems to be pried from settings, sold separately and then remounted as a way to avoid taxes. This practice is illegal and constitutes the crime of tax fraud, which has a sentence of three to seven years. While it is not illegal to pry gems from settings, and then sold as loose gems, if the gem is then remounted to the same exact setting or a visually similar setting, a crime is then committed. In order for the crime to not be committed, it has to be a visually different setting or type of jewelry. Because of this, there is a saying, "He's got a diamond (or another gem), which can no longer be put in a ring." The saying implies a wife or significant girlfriend/ fiancee/mistress has left him. This saying is also used for women to imply that a husband or significant boyfriend/fiance has left them as well.
Banks/ Bank Notes
Bank notes can be used as a means of trade, especially with large amounts of money. Bank notes are not considered legal tender in the sense that they can be traded freely as with vouchers. Bank notes must be connected to specific accounts. A person can use a banknote to pay a sum of money in their account to an individual or company. The banks have their own fees as to amounts transferred, depending on whether the receiver has an account with the bank, with another bank connected to their system, with another bank not connected to their system, or no accounts at all.
Typically, though not always, banks do not charge fees for money transfers within the bank. This is because no actual money is being exchanged, but a simple accounting process is recorded to show the transfer of funds.
Banks also try to avoid physical money transfers by trading funds within their system. They simply match up financial amounts between an array of clients to minimize the physical transfer of actual money. For example, if person A has 50 gold in Bank 1 that they want to transfer via banknote to person B, who has an account at Bank 2, Bank 1 and 2 will enter into a lunar communication. Bank 2 will realize that they have person C who wants to transfer 30 gold to person D who also has an account at Bank 1. Therefore, instead of Bank 1 sending 50 vouchers to Bank 2, and then Bank 2 sending 30 vouchers back, Bank 1 will simply send 20 vouchers to Bank 2. This minimizes the physical transfer of assets, lessens the cost of couriers, and minimizes the chances of robbery and the amount stolen when money is robbed en route.
Banks within the same system usually have a lunar board where they can see the transactions between the banks within their system. This allows them to do this kind of accounting manipulation between several banks at a time. For example, person A has 50 gold in Bank 1 that they want to transfer via banknote to person B, who has an account at Bank 2. Bank 1 which is a part of the same system of banks as Bank 2, posts the transfer to their lunar communication board. Bank 2 has person C wanting to transfer 30 gold to person D, who has an account at Bank 3, which is also in their system. Bank 3 has person E who wants to transfer 30 gold to person F, who has an account at Bank 1. This exchange would end with Bank 1 physically sending 20 gold to Bank 2, and no other funds being physically transferred, with the other transfers only being recorded on paper. Banks that are not within the same system can only do this kind of accounting manipulation between the two banks involved in the transfer. Because of this, transaction costs between banks in the same system will have lower transaction costs, while banks outside the system will have higher transfer costs. Transfers to individuals/businesses without accounts have the highest transaction costs, as the transfer is always the complete amount.
According to law, all bank transactions must be settled within two weeks. Therefore, transfers can take as little as 1 day, and as many as 14 days to transfer funds via banknotes. The duration is dependent on how long it takes for banks to match up transfer funds, and the actual physical transfer of money if that is required. Rush transfers, where the transfer is rushed to be completed within two days compel extra fees.
Another reason for limiting the physical transfer of actual money is that banks are required by law to keep at least 20% of their actual financial holdings in their vaults at any given time. Banks typically keep around 25% of their actual financial holdings to avoid breaking the law. For the rest of their financial holdings, they are free to lend to people asking for loans. The bank workers are typically paid with money made from these loans. The majority of banks do not charge their customers to keep their money at the bank.
Depending on the bank, customers can withdraw a certain amount of money from their account immediately, without waiting and without incurring a fee. Different banks have different rules of withdrawal, but typically do not charge an immediate withdrawal if the amount is under two gold in value. Larger amounts can be withdrawn, but they typically require a waiting period of at least a week, and up to a month depending on the amount the individual wishes to withdraw. Immediate withdrawal fees are higher the larger the amount withdrawn. These fees are detailed in the bank holder's contract that they sign at the time accounts are set up. Transfer fees are also detailed in these contracts prior to any transfers being made. This is to avoid people suing banks for taking too much of their money in fees.
According to law, banks are financially responsible for money being stolen. If a thief steals 10000 gold from a bank, the account holders still have the same amount of money in their accounts, and the banks must take the loss. Banks, therefore, do everything possible to ensure the security of their assets, including minimizing the amount of physical money being transferred; using armed, magical security; and gold lining their vaults. They also pay large bounties for the retrieval of assets stolen.
Banks also typically pay into an insurance fund within their system of banks that will pay a certain amount in case of theft or loss. These insurances typically do not pay the entire amount stolen, but the amount stolen up to a certain amount. This amount is dependent on how much money an individual bank pays into these funds. For example, Bank 1 might pay 1 gold a month into the fund to receive up to 100 gold in insurance payouts. Bank 2 might pay 2 bronze for 40 in coverage, and Bank 3 might pay 1 bronze for 10 gold in coverage. If 40 gold is stolen, Bank 1 would only receive 40 despite the 100 in coverage, since only 40 was stolen. Bank 2 would receive 40 gold, equal to the coverage and the amount stolen. Bank 3 would only receive 20 gold, even though 40 was stolen. This is because Bank 3 only had 10 gold worth of coverage.
Because the amount paid into the fund is smaller than the amount of coverage, insurance companies often require certain levels of security at individual banks. If sufficient security is deemed to not have been met, coverage could be lessened or outright denied. Security requirements must be detailed in insurance contracts beforehand in order to effect policy payouts. Addendums can be made to security requirements if insurance groups find a previously unknown weakness in the existing standards. However, if an addendum is made after the insurance contract is signed, the insured agencies have a month to respond if they wish to continue with their coverage under the new conditions. Then they have a month to comply with the new security measures. If money is stolen from the insured agency during this two-month period, no penalty can be incurred, as long as the previous standards were met. Only after this two-month period can the agency be penalized for not complying with the addendum to the security standards. Insurance funds might have multiple tiers in security requirements, where if security requirements are not met the insured individual has different levels of coverage. For example, if Bank 1, which pays 1 gold a month for 100 gold of coverage, has armed magical security, but not a gold-lined vault, they may have a 50% tier coverage, so they would only be eligible for 50% of the payout. Therefore, if 40 gold is stolen from them, even though they have 100 gold in coverage, they would still only be eligible for 20 gold, because the payout is equal to the amount stolen, or the amount covered, whichever is lower. After that, the 50% tier coverage is applied. This tier coverage applies, whether or not a security flaw was the reason for the money being stolen.
Credit Systems
Credit systems can be extended by stores or within organizations. An individual or business may purchase goods from another individual or business on credit, and settle those accounts at a later date, or in smaller payment amounts. Receipts of purchase are kept by both the lender and the borrower in case of financial disputes. Receipts must be signed by both the lender and borrower or a representative of either the lender or borrower. Additional receipts are created and given to both parties each time a payment is made.
Courts always side with the holder of the receipts when disputes are made. For example, if a purchase is made, but the receipt is lost by the lender, the borrower is not required to pay the credit. If a borrower pays an amount but loses the payment receipt, the lender can technically demand repayment from the borrower. Borrowers and lenders are required to keep all receipts associated with a transaction up to a year following the due date of the final payment. Disputes concerning a transaction can not be brought up past a year of the final payment date. The receipt of the original purchase must be held to bring a dispute to the court. If a payment is in the process of being disputed in the courts, all receipts must be held until the end of the court proceeding, even if the year mark has passed.
In order to be a representative, individuals must have a signed affidavit from the individual, business, or organization that they are representing, so they are able to borrow or lend on their behalf. Affidavits can be specific to the organizations or individuals the representative can borrow from/lend to, or put a cap on the amount specified on a per-day, per-month, or per-year basis, but not made for a one-time purchase use.
Suppose representatives violate the terms of the affidavit. In that case, they are financially responsible for the amount of money violating the agreement, and the payments/merchandise still go to the respective parties. For example, if a representative goes to a restaurant and has an affidavit to purchase up to 50 gold worth of meat from the butcher each month for their employer, but instead spends 60 gold worth of meat in a given month. That representative would be financially responsible to pay the 10 gold difference. This would be the case, even though the restaurant used the extra 10 gold of meat purchased on their behalf, and if the restaurant had not yet used that extra 10 gold worth of meat, the restaurant could decide whether or not to return the meat to relieve their representative of the financial burden (If the butcher will accept the return of the meat, of course. The lender has the right to refuse returns.), or the restaurant could keep the meat, and the representative would still be financially responsible for that extra 10 gold in costs. Whether or not the restaurant decides to keep or remove the borrowing rights of that representative does not change the financial burden that the representative incurred.
In order to remove an affidavit from a representative, another affidavit must be signed to void the first affidavit. The employer must produce the second affidavit in case a former representative is disputing in court their employer's failure to honor their borrowing/lending on the employer's behalf. Because of this, representative affidavits always have set expiration dates, so former representatives cannot continually bring these claims. If a representative is retained past the affidavit's expiration, a new affidavit must be signed to continue their position as representative. Government officials must sign all affidavits to be legally binding (government officials do not need to sign receipts of borrowing or payments, the borrows/lenders/representative signatures are sufficient for legal purposes in court).
While representatives are legally required to have affidavits to be legal representatives, it is not an uncommon practice for employers to have non-legal representatives buy or lend goods on credit on their behalf. This is especially the case for one-time purchases. If this is done, employers must sign a list of specific items allowed for purchase or sign the credit receipt to acknowledge and accept the financial responsibility of the purchase or lending. If either one of these signatures is not signed, the representative is dependent on the employer to honor their verbal agreement with the representative. If the employer does not honor the purchase, the non-legal representative is required to pay the entire amount, as if they had made the purchase themselves or purchased the good from their employer and then lent it to the purchaser themselves. However, if this is done, the non-legal representative also receives the financial benefit of that purchase. If the employer takes the product or any interest associated with the lending but does not honor their verbal commitment to the non-legal representative, the non-legal representative can sue their employer (or former employer) for the right to the property or financial benefit from the use or sale of the goods or services purchased on credit.